
You’ve got a hospital bill sitting in the back of your inbox, the one you keep telling yourself you’ll deal with next month. Then one Tuesday it stops being a bill and becomes a summons. That jump feels sudden. It is also happening to more people than ever this year, and the part that catches most people off guard is that the lawsuit doesn’t even need the debt collector to show up and win. Silence does that job for them.
So if you’re the kind of person who reads training programs before buying them, here’s the data on what’s driving the surge, what actually happens after you’re served, and how to protect your paycheck and your bank account before a judgment makes the decision for you.
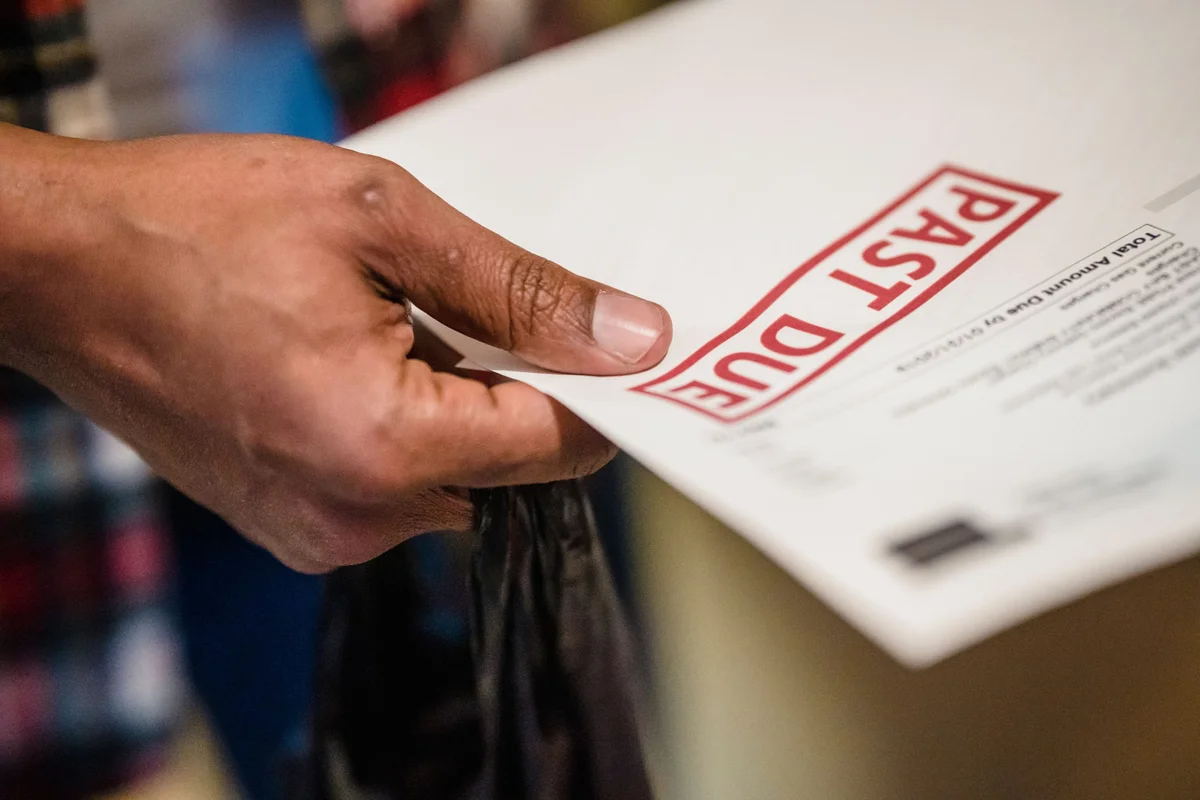
Why medical debt lawsuits are climbing in 2026
The short answer: filings have climbed back toward pre-pandemic highs, and medical bills are one of the top reasons households end up in court alongside credit card and bank debt. A Pew Charitable Trusts analysis of state court data put debt collection filings at 4.7 million cases in 2022, with the trend continuing through 2023 and 2024 and several states now past their post-2008 recession peaks. Utah is on track to break its own record this year, and Alabama has already hit its highest filing level ever recorded.
Third-party debt buyers are a big part of the story. One of them, LVNV Funding, increased its case filings by 350% between 2019 and 2024 and accounted for nearly a quarter of all filings in the states Pew tracked closely. In Virginia alone, hospitals and physician groups have filed more than one million lawsuits against patients since 2010.
And the credit-report angle still matters: a court judgment can follow you even after the original bill disappears from your report, so the lawsuit is where most of the damage actually gets done.
What actually happens after you are served
Getting sued starts with a summons and complaint — a formal notice that a case has been filed and that you have a set window, usually 20 to 30 days depending on your state, to file a written response. Miss that deadline and the case does not just sit there. The court typically enters a default judgment automatically, which means the collector wins without ever having to prove the bill is accurate or that you actually owe it.
From there, a judgment creditor can move to garnish your wages or freeze funds in your bank account, depending on what your state allows. That outcome is common because so few people respond. A Michigan resident recently had 25% of her wages garnished for more than eight weeks over a five-year-old utility debt, and the pattern plays out just as often with medical bills once a judgment is entered.
Here’s the practical part: responding to the summons, even with a short written answer that disputes the amount or asks for proof of the debt, stops the automatic default and forces the collector to actually prove its case.
Wage garnishment for medical debt is legal in most states
Unlike federal student loans, which carry specific consumer protections, wage garnishment for an unpaid medical bill is legal in all but a handful of states once a creditor has a court judgment in hand. In Colorado alone, an estimated 14,000 medical debt cases result in court-approved wage garnishment every year, a pattern KFF Health News has documented across rural hospitals, physician groups, and even public ambulance services.
That has pushed eight states, including Colorado, Florida, Indiana, Michigan, and Ohio, to introduce legislation this year to ban or sharply limit garnishment for medical debt, following Arizona, which passed similar protections in 2022.
The bank-account side is thinner protection still. Only about a third of states currently guarantee any automatic protection for a bank account tied to a judgment. Virginia just became the 14th state to add one, shielding the first $1,000 in an account from seizure. Outside of states with that kind of rule, a judgment creditor can freeze an entire account balance — including money meant for rent or groceries — until the debt is satisfied or you successfully claim an exemption in court.
Quick note before you start reading state-by-state rules: this is general information, not legal advice. Garnishment and exemption rules vary by state, so consult an attorney in your state before you rely on any specific number here.
And context on how little legal help most people get: a Pew Charitable Trusts review of court data found that consumers are represented by an attorney in fewer than 10% of debt collection cases nationwide, and in some jurisdictions that figure drops below 1%.
How to protect yourself if you are sued
Ignoring the summons is the most expensive mistake you can make, since it triggers an automatic default judgment. The steps that actually move the needle:
- File a written response by the deadline on the paperwork. A short one is fine — the goal is to stop the default and force the collector to prove its case.
- Request an itemized bill from the hospital or debt buyer. Confirm the amount is accurate and actually yours before you negotiate anything.
- Ask about financial assistance. Many hospitals are required to offer charity care under IRS rules for nonprofit facilities, and asking about that program, even after a bill has gone to collections, can sometimes reduce or eliminate what you owe retroactively.
Once you are in front of a judge, or before the hearing if the collector is willing, ask for a payment plan capped at an amount you can actually sustain rather than accepting whatever the collector proposes first. Free legal aid clinics in many counties specifically handle debt collection defense and can check whether the debt buyer even has the paperwork to prove you owe the amount claimed — which is a common weak point in these cases.
When to get help before it reaches court
The cheapest time to fix a medical bill is before it becomes a lawsuit. A nonprofit credit counselor through the National Foundation for Credit Counseling can review medical bills alongside every other balance you are carrying and flag which ones are worth disputing before a collector files anything.
Calling the hospital’s billing office directly, before a bill is sold to a third-party debt buyer, is often the easiest point to negotiate a reduction or an interest-free payment plan. Providers generally recover less once a case goes to an outside collector, and the lawsuit is where that number drops the most.
If medical bills are one of several balances pushing your finances past what feels manageable, it also helps to understand your options — like how Chapter 7 and Chapter 13 differ — before a judgment forces that decision for you.
The Science, Simplified
A medical debt lawsuit is less about the hospital and more about timing. Most people who get served never respond, and the default judgment that follows is what turns a bill into a wage garnishment or a frozen bank account. Answer the paperwork by the deadline, demand the itemized bill, ask about charity care, and the collector has to actually earn its win instead of getting one by default. That one response is the single step most likely to change how this ends.
Photo: Nicola Barts / Pexels
Leave a Reply